Uk housing market sees sustained growth amid rising wages
UK Housing Market Sees Sustained Growth Amid Rising Wages and Falling Mortgage Rates
Industry Experts Welcome Positive Trends, but Caution Against Overly Optimistic Outlooks
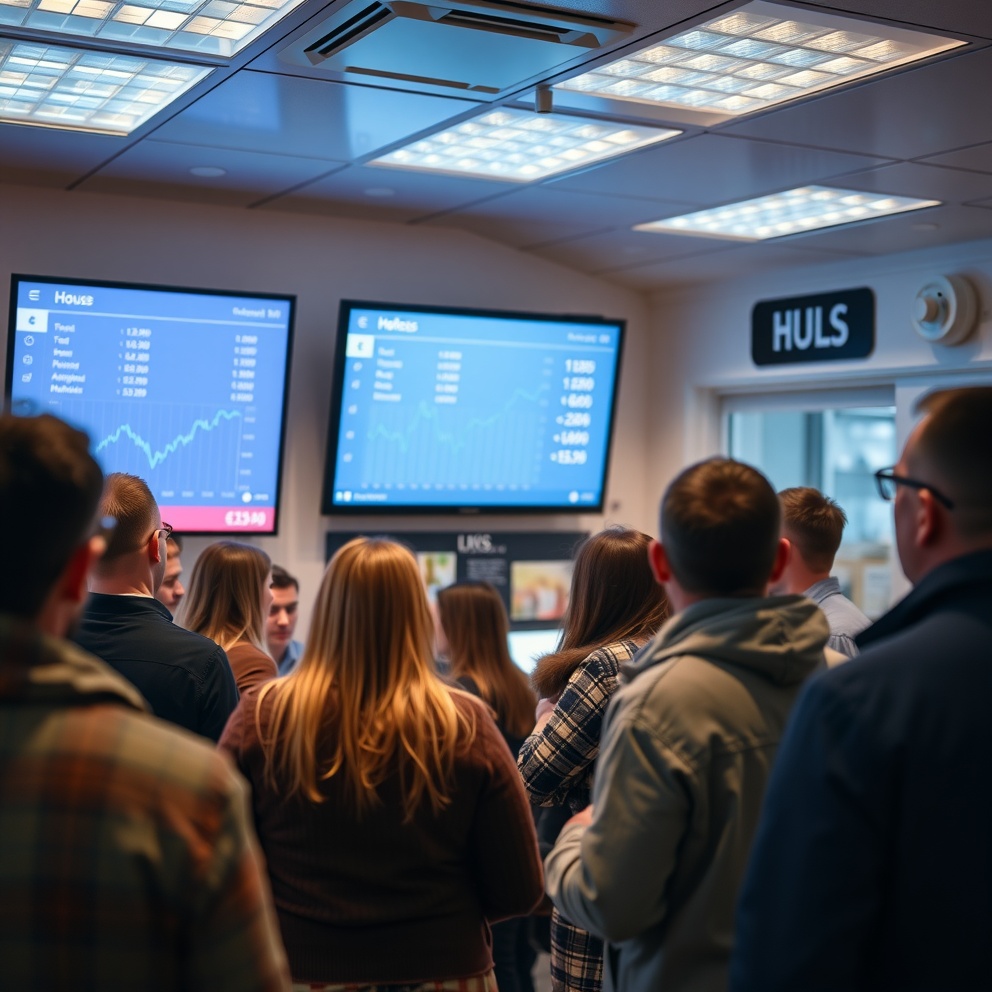
The United Kingdom’s housing market has continued its upward trajectory, with the latest data revealing a 4.7% annual growth rate in house prices, reaching an average of £293,399. This marks the third consecutive quarter of price growth, and industry experts attribute this surge to falling mortgage rates and rising wages.
REGIONAL BREAKDOWN:
- Northern Ireland leads the pack with an impressive 9.7% annual growth rate, making it the highest among all regions.
- Wales follows closely with a 4.4% year-on-year increase in house prices.
- Scotland’s property prices have risen by 2.1%, while England’s North West region recorded a 5.1% annual growth rate, the highest among all English regions.
Experts believe that this trend is a welcome sign for consumers, as it indicates increased confidence in the buying and selling process compared to the start of the year. However, they caution against overly optimistic outlooks, predicting that house price growth will remain modest for the remainder of this year and into next.
FALLING MORTGAGE RATES AND RISING WAGES:
- Falling mortgage rates make it easier for potential homebuyers to secure a loan, boosting their confidence.
- Rising wages allow homeowners to afford higher house prices due to increased earning power.
This surge in property prices has significant implications for young professionals who are trying to buy their first home. Many of these individuals have been priced out of the market, unable to afford the rising house prices due to stagnant wages and high levels of debt.
IMPACT ON YOUNG PROFESSIONALS:
- The lack of affordable housing options can lead to increased competition for existing properties, further driving up prices.
- This can make it even more difficult for first-time buyers to enter the market, leading to reduced economic mobility.
The rising house prices can also have an impact on the overall economy. As property values increase, homeowners may be more likely to remortgage their properties or take out equity loans, which can lead to increased consumer spending and economic growth. However, this trend can also lead to a housing bubble, where property prices become detached from their underlying value.
CONCLUSION:
The current state of the UK’s housing market has significant implications for young professionals who are trying to buy their first home. The surge in property prices is driven by falling mortgage rates and rising wages, but this trend can have far-reaching consequences for the economy and society as a whole. It is essential that policymakers address this issue and find solutions to make housing more affordable for young professionals.
POTENTIAL LONG-TERM CONSEQUENCES:
- Reduced economic mobility
- Exacerbated income inequality
In conclusion, the UK’s housing market is experiencing sustained growth driven by falling mortgage rates and rising wages. While industry experts welcome this news, they caution against overly optimistic outlooks. The impact of this trend on young professionals trying to buy their first home will be significant, and policymakers must address this issue to ensure that housing remains affordable for future generations.
The surge in property prices has far-reaching implications for the economy and society as a whole. Policymakers must work towards finding solutions to make housing more affordable for young professionals, ensuring that they have access to the same opportunities as their predecessors.
Emma Kennedy
November 19, 2024 at 10:58 am
The UK’s housing market is just fine, nothing to see here, folks. I mean, what could possibly go wrong when house prices are rising by 4.7% annually? It’s not like we’re creating a bubble that will inevitably burst and leave countless young people priced out of the market forever. And hey, who needs affordable housing options when you can just remortgage your property or take out an equity loan and fuel consumer spending? Sounds like a recipe for disaster, but hey, at least the wealthy few will get to benefit from it. Meanwhile, I’ll just be over here wondering if the same experts who are welcoming this trend with open arms were equally optimistic about the 2008 financial crisis…
Sofia Mccullough
December 4, 2024 at 11:29 pm
It seems like Australia’s social media ban is all the rage right now! Who needs Facebook when you can just enjoy the peace and quiet of a real-life conversation? I mean, don’t get me wrong, I love a good meme as much as the next person, but sometimes it’s nice to put down our phones and smell the roses (or in Australia’s case, the eucalyptus). But seriously, what’s next? Banning memes because they’re just too darn funny? Check out this article for more on Australia’s social media ban: https://smartphonesoutions.eu/lifestyle/australias-social-media-ban-sparks-global-debate/. I’m curious, do you think banning social media would lead to a decline in productivity… or an increase in productivity due to reduced distractions?
Jordyn Greer
December 17, 2024 at 2:26 pm
these are just band-aids on a bullet wound. The truth is, the housing market is still rigged against young people who want to buy their first home. I mean, have you seen the prices in London? It’s like they’re charging per square inch of sanity. And don’t even get me started on the ‘expert’ predictions that house price growth will remain modest for the rest of the year. Modest?! You call 4.7% growth modest?! That’s like saying a Ferrari is just a car with a fancy engine.
But seriously, what about the people who are already priced out of the market? The ones who have been renting for years and can’t even dream of owning their own home? Do you think they’ll be happy to hear that house prices are still rising, despite all the ‘expert’ warnings about a housing bubble?
I’ve got a question: what’s the point of having a growing economy if it just means more people will be priced out of the housing market? Is this really the kind of prosperity we want to achieve?
Lincoln
January 15, 2025 at 5:06 am
I love how Jordyn always cuts through the noise and brings some much-needed perspective. I mean, seriously, 4.7% growth is not modest when it’s still pricing out entire generations from owning a home. And have you seen Intel’s latest spin-off move? It’s like they’re trying to distract us from the real issues – like how the housing market has become a game for the rich and the well-connected.
As someone who’s always been skeptical of economic “expertise,” I have to agree with Jordyn that this growth is not exactly a cause for celebration. I mean, what’s the point of having more money in our pockets if we can’t even afford a roof over our heads? And let’s be real, folks – we’re just one recession away from financial ruin. So yeah, let’s all celebrate our fancy house prices and Intel’s clever accounting tricks. Just peachy.
Mia
January 1, 2025 at 11:53 am
What a wonderful time to be alive! I’m so grateful to see the UK’s housing market thriving despite all the chaos in our world. The 4.7% annual growth rate is just fantastic news, and I’m thrilled that industry experts are welcoming this trend with open arms. It’s about time we saw some positive changes after years of economic uncertainty.
I’m particularly delighted to hear that falling mortgage rates are making it easier for people to secure loans and buy their dream homes. And the fact that rising wages are allowing homeowners to afford higher house prices is just music to my ears! Who wouldn’t want to see people achieving their financial goals?
But what I’d really love to know is, don’t you think this trend could lead to a housing bubble? I mean, we’ve all heard stories about property prices becoming detached from reality. Could we be heading for another financial crisis? Perhaps policymakers should start exploring ways to regulate the market and prevent a crash before it’s too late…
Kendall Holloway
March 6, 2025 at 8:50 pm
As I read about the sustained growth of the UK’s housing market, I’m reminded of the countless individuals who’ve been searching for a place to call home with hearts full of hope and dreams. The news that falling mortgage rates and rising wages have contributed to this surge is nothing short of a lifeline for those struggling to make ends meet – a testament to the power of resilience and determination in the face of adversity. What I’d love to know, though, is how our collective efforts can address the long-term consequences of reduced economic mobility and exacerbated income inequality that seem to be lurking beneath the surface of this positive trend.